NOVEMBER 3, 2026
Aluminum Metals Market Rebounds as China Demand Doubts Meet Tight Supply SignalsAluminum steadies as traders weigh slower China demand, tight supply and dollar moves after a volatile start to November metals trading.

© 1box.site 2026
NOVEMBER 9, 2026
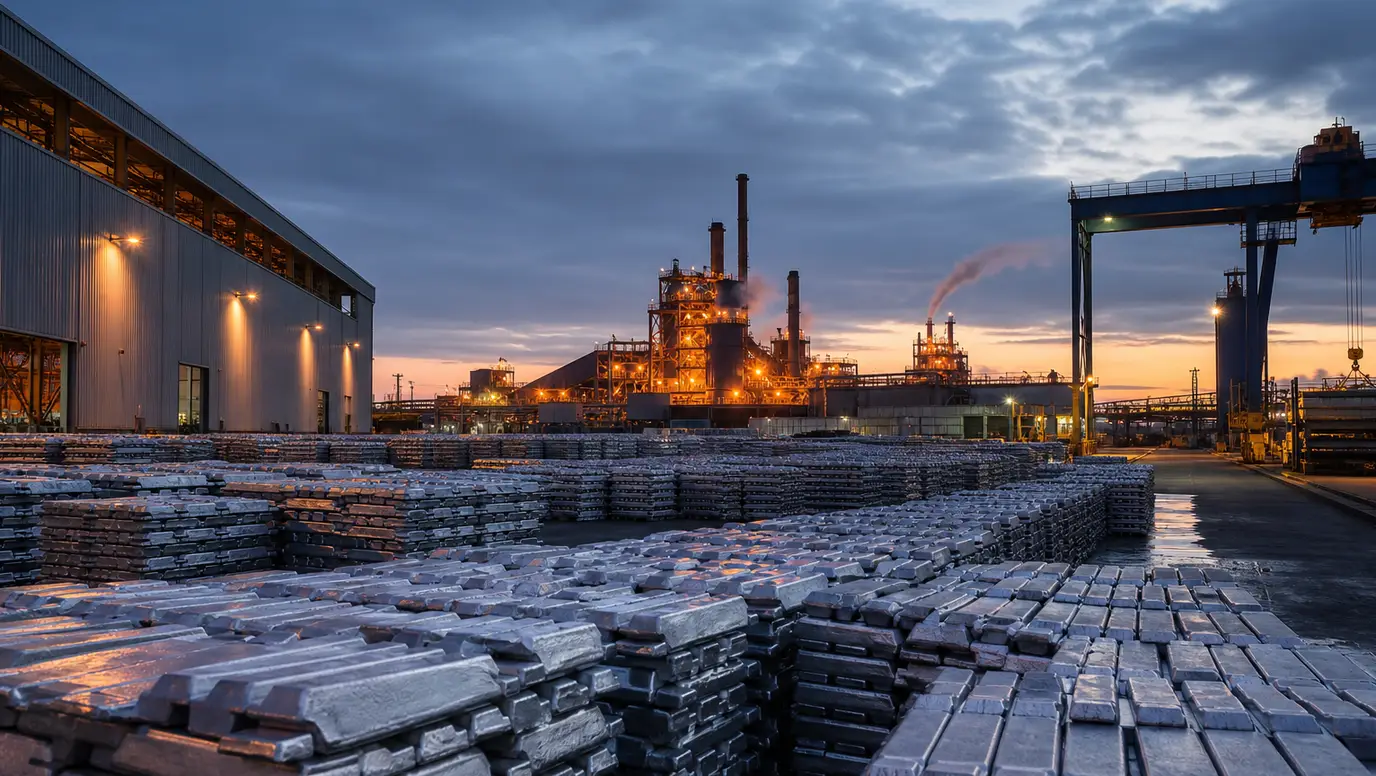
Aluminum traded in a narrow range on Monday as the metals market weighed a gradual recovery in global smelter supply against still-tight visible inventories and uneven downstream demand. Three-month aluminum was holding close to the $3,070-per-ton area, leaving the contract little changed after a volatile autumn rally and pullback.
The latest move reflects a more balanced tone than the sharp supply-squeeze trade seen earlier in the year. Traders are no longer chasing aluminum purely on disruption risk, but they are also reluctant to price in a rapid surplus while exchange stocks remain low by historical standards and regional premiums continue to show signs of physical tightness.
The bearish side of the aluminum story is becoming easier for the market to see. Several smelting operations outside China have been moving back toward normal output, while new capacity in Asia is adding to expectations that refined supply will improve into 2027. That has encouraged some forecasters to trim near-term price expectations, even as they keep a relatively firm floor under the market.
For futures traders, the key question is whether recovering production can arrive quickly enough to loosen spot availability. Aluminum is highly energy-intensive, so power costs and grid reliability remain central to the supply outlook. Any setback at smelters in power-constrained regions could quickly revive concerns over availability, especially with inventories still lean.
China remains the other decisive variable. Domestic aluminum prices rose modestly in the latest session, but processing-sector indicators have cooled as the traditional peak demand season fades. That mixed signal has kept the market from breaking decisively higher: construction demand remains selective, while transportation, packaging and power-grid applications continue to provide a steadier industrial base.
Inventory data are preventing a more aggressive bearish turn. Exchange-held aluminum stocks remain near multi-year lows, and Chinese social inventories have continued to decline in several key regions. That suggests the market is not yet dealing with an obvious oversupply of deliverable metal, even if the direction of supply is improving.
This tension between better output and thin stocks is visible in spreads and spot-market behavior. When nearby material commands a premium, it signals that buyers still value prompt delivery. That can limit downside pressure even when macro investors become more cautious on industrial metals.
The broader macro backdrop is also important. A firm US dollar and elevated Treasury yields can reduce investor appetite for dollar-denominated commodities, while hopes for eventual monetary easing can support cyclical metals by improving the outlook for manufacturing and construction. Aluminum has therefore become a two-sided trade rather than a simple supply-squeeze story.
For the rest of the week, traders will watch whether aluminum can hold the $3,050 area on dips. A sustained move below that zone would suggest the supply-recovery narrative is gaining control, while a rebound above $3,120 could indicate that low inventories and physical premiums are still strong enough to challenge bearish forecasts.
Until clearer demand confirmation arrives, aluminum is likely to remain range-bound. The market has moved past the panic phase of the supply story, but it has not yet built the inventory cushion usually needed for a deeper and more durable price decline.
NOVEMBER 3, 2026
Aluminum Metals Market Rebounds as China Demand Doubts Meet Tight Supply Signals
OCTOBER 26, 2026
Aluminum Metals Market Tightens as Exchange Stocks Fall and Tariff Flows Keep Premiums Elevated
OCTOBER 14, 2026
Aluminum Metals Futures Hold Near $3,000 as Japan Premium Drop Masks Supply Stress
OCTOBER 7, 2026
Aluminum Rebound Tests Metals Market as Dollar Strength and China Lull Cap Buyers
OCTOBER 1, 2026
Aluminum Slumps to 12-Week Low as Strong Dollar Hits Metals Market
SEPTEMBER 24, 2026
Aluminum Futures Steady as China Destocking Offsets Metals Market Yield Pressure
SEPTEMBER 16, 2026
Aluminum Rally Tests China Supply Cap as Metals Market Weighs Export Surge
SEPTEMBER 6, 2026
Aluminum Futures Split Metals Market as Supply Risk Meets Soft China Demand
AUGUST 31, 2026
Aluminum Premiums Rebound as Metals Market Tracks Tariff Risk and Alumina Squeeze
AUGUST 15, 2026
Aluminum Keeps Metals Market on Inventory Watch as China Demand Offsets Tariff Risk
AUGUST 4, 2026
Aluminum Premium Squeeze Keeps Metals and Commodities Traders Focused on U.S. Tariffs
JULY 29, 2026
Aluminum Stockpile Drain Puts Metals and Commodities on Premium Watch
JULY 21, 2026
Aluminum and Copper Rally Puts Metals Market on Tariff Watch
JULY 9, 2026
Copper Retreats as Gulf Tension Turns Base Metals Toward Demand Risk
JULY 8, 2026
Gold Loses Haven Bid as Dollar Strength Splits the Metals Market
JULY 3, 2026
Aluminum and Copper Rebound as Softer Dollar Revives Base Metals Demand
JULY 1, 2026
Copper Leads Metals Lower as Tariff Uncertainty Hits Aluminum and Zinc