OCTOBER 7, 2026
Japanese Yen Forex Weakens as USD/JPY Tests 158 Before Fed MinutesJapanese yen weakens as USD/JPY holds near 158, with Fed rate signals and Bank of Japan tightening bets driving forex market caution.

© 1box.site 2026
OCTOBER 7, 2026
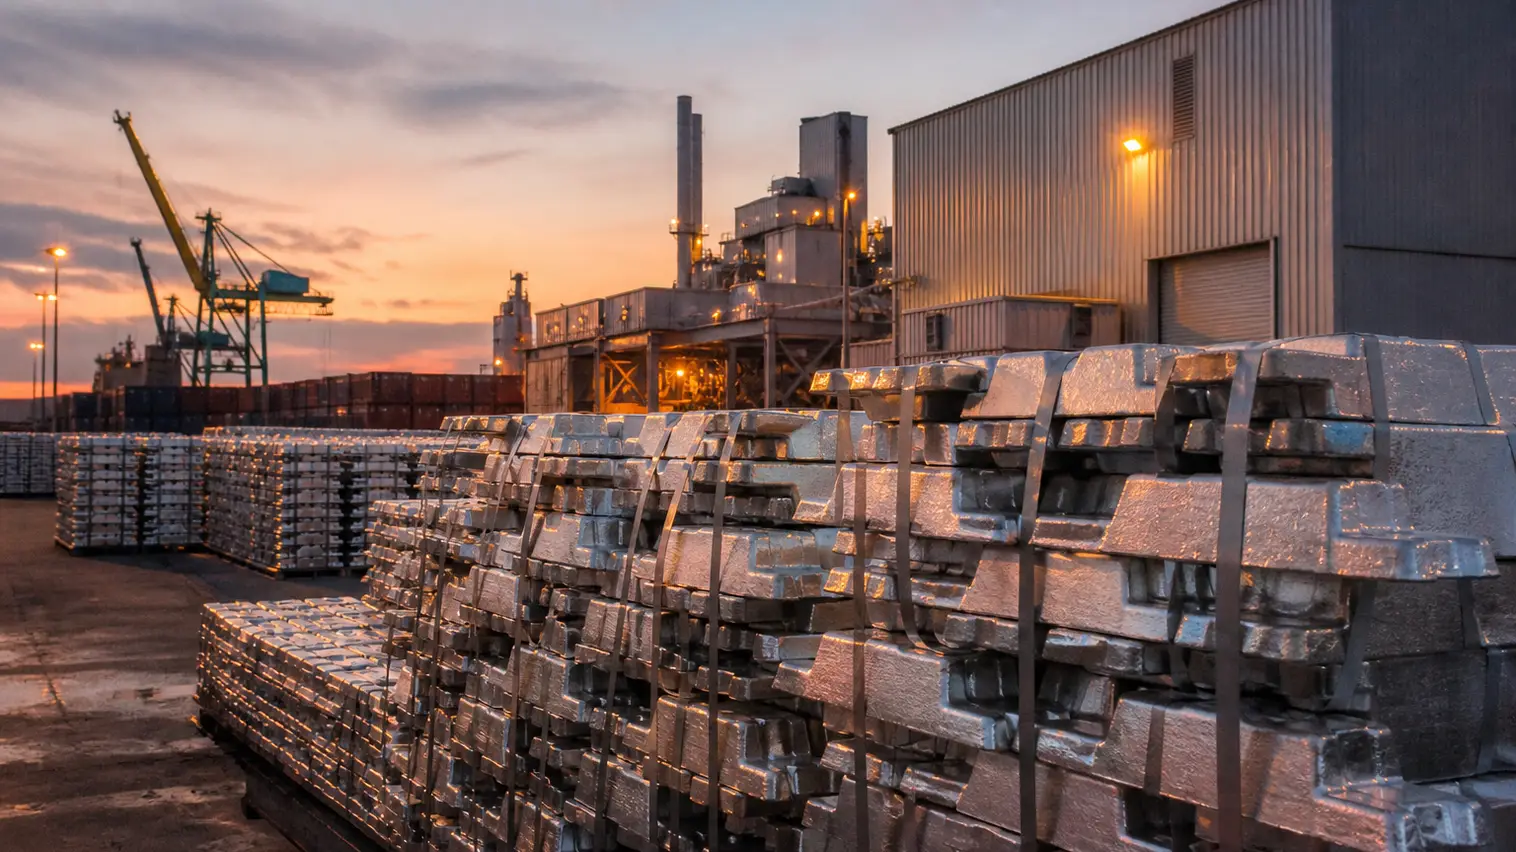
Aluminum moved back into the metals market spotlight on Wednesday after a sharp pullback from late-September highs left traders weighing whether the latest bounce is a durable recovery or only a pause in a broader correction.
The London market has been under pressure since the end of September, when aluminum retreated from elevated levels as macro headwinds, profit-taking and thinner China-related demand flows combined to cool the rally. After falling below the $3,150-per-ton area, the metal attempted to stabilize this week, but buying interest remained measured as the US Dollar stayed firm and Treasury yields kept financial conditions tight.
The current setup makes aluminum one of the more active metals stories of the session. Gold, silver and copper remain sensitive to the same dollar and rates backdrop, but aluminum is facing an additional test from physical-market signals, including cautious spot demand ahead of China’s post-holiday reopening and weaker regional premium indicators.
Traders are watching China’s return from the National Day holiday for clearer evidence of whether downstream restocking can revive demand. Before the break, buying had turned more selective, and the market now needs confirmation that fabricators and industrial consumers are willing to rebuild inventories at current price levels.
That demand question matters because aluminum’s recent decline did not come from a single bearish catalyst. Instead, it reflected a combination of weaker near-term liquidity, concern over whether peak-season consumption is strong enough, and a broader pullback across base metals as investors reduced exposure to cyclical commodities.
Japan’s quarterly aluminum premium also points to a more cautious physical tone. A lower premium for fourth-quarter shipments suggests regional buyers are not chasing units aggressively, even as some supply risks remain in the background. For traders, that weakens the argument for a rapid return to the late-September highs unless Chinese demand improves quickly.
The US Dollar remains a central pressure point for aluminum and the wider metals market. A stronger dollar raises the effective cost of dollar-priced commodities for many overseas buyers, while elevated Treasury yields make it harder for non-yielding and inventory-heavy assets to attract fresh speculative inflows.
That macro backdrop is limiting the impact of supply-risk headlines. Energy-market tension and possible disruptions to trade routes can support aluminum through higher production and freight concerns, but those factors have not yet been strong enough to fully offset softer physical demand signals.
For now, the near-term trading range is likely to be defined by whether aluminum can hold above the recent lows near the $3,100-per-ton zone. A sustained move back above $3,150 would suggest buyers are returning after the holiday lull, while renewed weakness below recent support could invite another round of liquidation from funds that entered the market during the September advance.
The aluminum rebound is therefore less about a single price move and more about confirmation. Bulls need stronger post-holiday activity from China, firmer regional premiums and a softer dollar to rebuild momentum. Bears will focus on any evidence that demand remains cautious or that elevated US yields continue to drain appetite from industrial metals.
Until those signals become clearer, aluminum may trade with a defensive recovery bias rather than a full bullish reversal. The metal remains supported by long-term themes such as electrification, grid expansion and lightweight manufacturing demand, but the immediate market is being driven by currency pressure, inventory discipline and the speed of China’s return to normal trading conditions.
OCTOBER 7, 2026
Japanese Yen Forex Weakens as USD/JPY Tests 158 Before Fed Minutes
OCTOBER 6, 2026
British Pound Forex Steadies as Firm US Dollar and Gilt Yields Cap GBP/USD Bounce
OCTOBER 5, 2026
Australian Dollar Forex Holds Below 70 Cents as Reserve Bank of Australia Hike Meets Firm US Dollar
OCTOBER 4, 2026
Canadian Dollar Forex Slips as U.S. Rate Gap and Flat GDP Keep USD/CAD Near Highs
OCTOBER 2, 2026
Silver Holds Above $61 as Dollar and Treasury Yields Keep Metals Market on Payrolls Watch
SEPTEMBER 30, 2026
Swiss Franc Forex Rebound Tests US Dollar Rally as Federal Reserve Inflation Gauge Cools
SEPTEMBER 22, 2026
Japanese Yen Slides as Dollar Strength and Bank of Japan Doubts Put Forex Market on Intervention Watch
SEPTEMBER 15, 2026
Euro Slides as US Dollar Rally Puts Forex Market on Federal Reserve Watch
SEPTEMBER 11, 2026
Japanese Yen Firms in Forex Market as Bank of Japan Bets Challenge US Dollar Rally
SEPTEMBER 6, 2026
Euro Firms in Forex Market as European Central Bank Decision Sets Up Dollar Test
SEPTEMBER 1, 2026
Swiss Franc Weakens as Forex Market Backs Dollar on Federal Reserve Rate Risk
AUGUST 27, 2026
US Dollar Rebound Tests Forex Market as Hot PCE Revives Fed Rate Risk
AUGUST 21, 2026
Dollar Slide Puts Forex Market on Treasury Yields Watch as Fiscal Fears Spread
AUGUST 20, 2026
Euro Forex Rally Holds as US Dollar Weighs Hawkish Federal Reserve Minutes
AUGUST 19, 2026
Swiss Franc Takes Forex Funding Spotlight as Dollar Rate Gap Stays Wide
AUGUST 18, 2026
Stablecoin Liquidity Squeeze Puts Cryptocurrency Market on US Dollar Rail Watch
AUGUST 13, 2026
US Dollar Drifts as Soft PPI Pulls Treasury Yields Into Federal Reserve Forex Focus
AUGUST 12, 2026
British Pound Rises as Softer US CPI Hits US Dollar and Resets Bank of England Watch
AUGUST 11, 2026
Forex Market: Japanese Yen Weakens as US Dollar Rebound Tests Intervention Risk Before CPI
AUGUST 9, 2026
Swiss Franc Holds Near US Dollar Pivot as SNB Intervention Warning Shapes Forex Market
AUGUST 8, 2026
Forex Market: New Zealand Dollar Stalls Against US Dollar as Reserve Bank Path Turns Data-Heavy
AUGUST 7, 2026
Forex Market: Euro Rallies as US Dollar Slides After Payrolls Shock Tests Federal Reserve
AUGUST 6, 2026
Forex Market: Canadian Dollar Firms Before Jobs Data as US Dollar Momentum Fades
AUGUST 6, 2026
Zinc Inventory Draw Keeps Metals Market Focused on China Supply and US Dollar Risk
AUGUST 5, 2026
Japanese Yen Intervention Keeps Forex Market Focused on US Dollar Risk
AUGUST 3, 2026
Copper Rebound Puts Metals Market on US Dollar Watch as Supply Tightness Offsets Demand Caution
AUGUST 3, 2026
Australian Dollar Firms as Reserve Bank of Australia Outlook Tests US Dollar
AUGUST 2, 2026
New Zealand Dollar Faces RBNZ Test as US Dollar Jobs Risk Looms
AUGUST 1, 2026
Euro Rebound Tests US Dollar as Forex Traders Weigh ECB and Federal Reserve Divide
AUGUST 1, 2026
Silver Slide Puts Metals Market on Fed Watch as US Dollar Reasserts Pressure