OCTOBER 8, 2026
PepsiCo Stock Climbs as Earnings Beat Meets North America WarningPepsiCo stock rises after a Q3 beat, but weaker North America demand and a reduced 2026 EPS outlook keep investors focused on margins.

© 1box.site 2026
OCTOBER 9, 2026
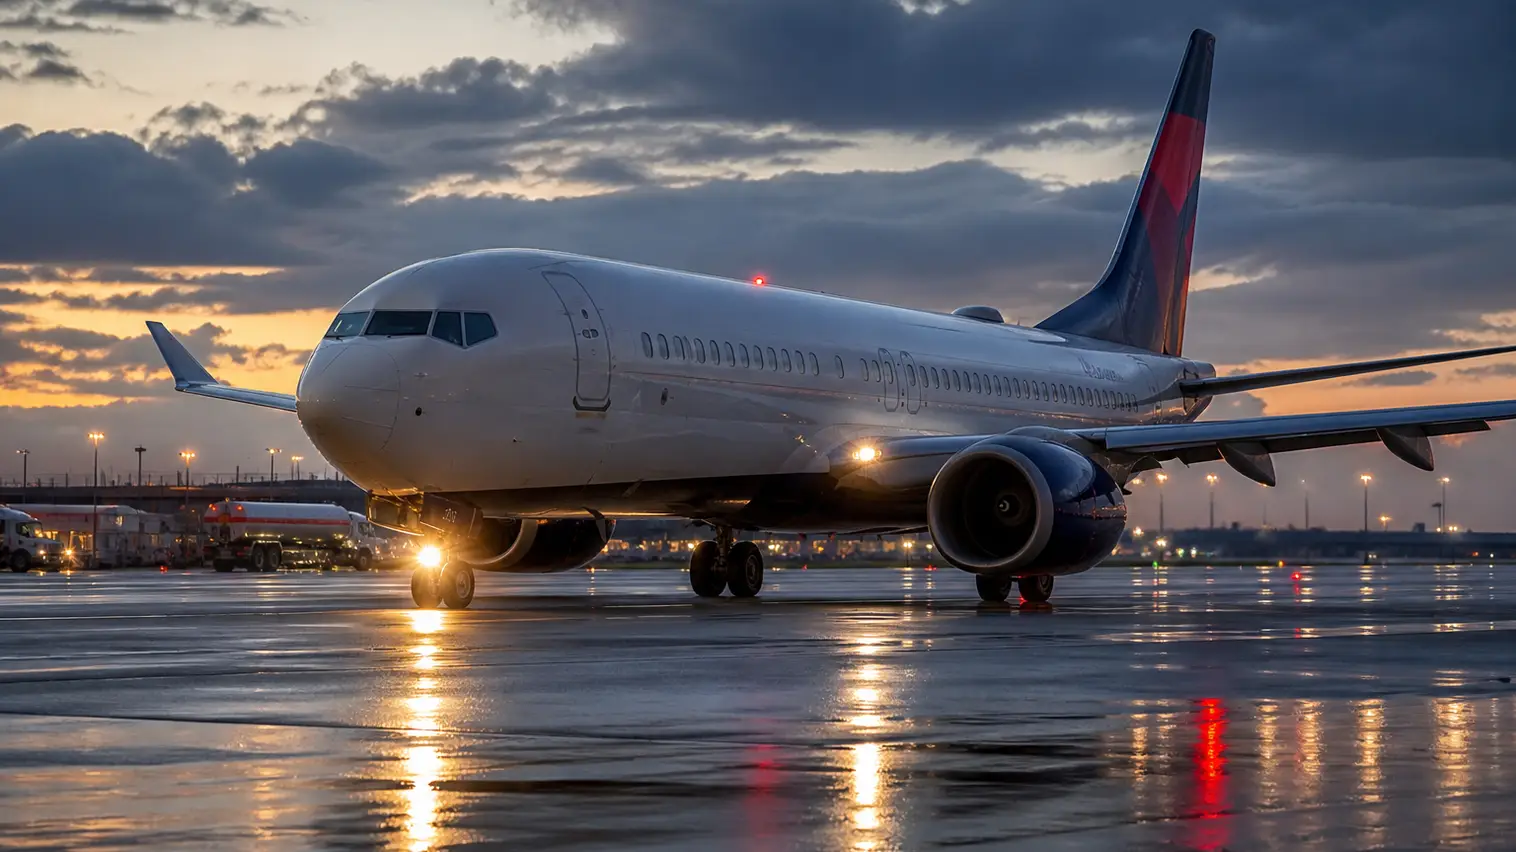
Delta Air Lines stock moved into the spotlight on Friday after the carrier lowered its full-year profit outlook, making airline shares one of the clearest single-stock stories in an otherwise cautious market. The update underscored a familiar tension for investors: travel demand remains resilient, but elevated fuel prices are absorbing more of the benefit from higher fares and fuller premium cabins.
The company reported record September-quarter revenue and pointed to continued strength in consumer and corporate travel. Still, the market focused on the revised earnings outlook. Delta now expects full-year adjusted earnings per share of $5.10 to $5.60, a notable reduction from the stronger target range it had previously indicated. The cut placed fresh pressure on the stock because it suggested that revenue momentum alone may not be enough to protect margins in a high-cost operating environment.
For the stock market, the update matters beyond one carrier. Delta is often treated as an early read on travel demand, discretionary spending and business confidence. Its results arrived as investors were already balancing higher oil prices, firm Treasury yields and the upcoming start of the broader earnings season. That made the airline’s guidance especially important for traders assessing whether corporate profits can withstand higher input costs.
The central issue in Delta’s report was not weak demand. Management described travel appetite as strong and highlighted broad revenue support across the network. Instead, the pressure came from fuel, which has become a larger and more unpredictable expense for airlines as crude oil and refined product markets remain volatile.
Fuel is especially important for airline stocks because carriers have limited control over the timing and scale of price moves. Strong ticket pricing can help offset higher costs, but investors typically become cautious when fuel expenses rise faster than revenue per seat. That is the risk now facing Delta and its peers: demand may be durable, but the profit conversion from each dollar of revenue becomes less certain.
Delta also pointed to full-year free cash flow of about $2.5 billion and continued debt reduction plans. Those details may help limit the downside narrative because they suggest the balance sheet remains a priority. Even so, equity investors are likely to focus on whether the carrier can defend margins into the December quarter while fuel remains elevated.
The stock reaction also reflects a broader valuation question. Airline shares can rally when investors see a combination of strong bookings, disciplined capacity and easing fuel costs. When one of those pillars weakens, the sector often becomes more vulnerable to earnings revisions. Delta’s update showed that demand strength is still present, but the cost line is now driving the debate.
Delta’s report could set the tone for airline stocks as investors prepare for additional corporate results. If other carriers echo the same pattern of solid revenue but pressured margins, the market may become more selective across the group. Companies with stronger premium exposure, loyalty revenue and balance-sheet flexibility may hold investor confidence better than carriers with thinner margins or heavier exposure to price-sensitive travelers.
The timing is important because the wider stock market is entering earnings season with less room for disappointment. Major indexes have been sensitive to Treasury yields and oil prices, while investors continue to question how much of the year’s profit optimism is already reflected in share prices. In that setting, guidance cuts can have an outsized impact, even when headline revenue looks healthy.
For Delta, the next phase of the story will depend on whether investors treat the profit cut as a temporary fuel shock or a sign that airline margins have peaked for this cycle. A stabilization in energy prices would improve the case for a rebound, especially if travel demand remains firm through the holiday period. However, another leg higher in fuel costs could keep pressure on airline valuations and make earnings estimates vulnerable to further reductions.
The market message from Delta’s update is therefore mixed but clear. Consumers are still flying, premium demand remains supportive and revenue trends are not the immediate problem. The challenge for the stock is that higher fuel costs are now limiting the earnings upside that investors had expected from that demand. Until fuel volatility eases, Delta Air Lines stock and the broader airline group may remain a test case for how Wall Street prices strong sales against shrinking margin confidence.
OCTOBER 8, 2026
PepsiCo Stock Climbs as Earnings Beat Meets North America Warning
OCTOBER 4, 2026
Nvidia Stock Hits Record as AI Buyback Puts Cash Returns in Focus
OCTOBER 3, 2026
Synaptics Stock Jumps as onsemi Semiconductor Deal Turns to $5.7 Billion Cash Offer
OCTOBER 2, 2026
Nike Stock Slides as Revenue Miss and China Weakness Deepen Turnaround Test
OCTOBER 1, 2026
Stacks STX Jumps as Bitcoin DeFi Yield Narrative Revives Crypto Market Rotation
SEPTEMBER 30, 2026
Carnival CCL Stock Holds Rally as Record Earnings Put Cruise Shares Back in Focus
SEPTEMBER 28, 2026
Vail Resorts Stock Faces Earnings Test as Investors Watch Pass Sales and Weather Risk
SEPTEMBER 23, 2026
IonQ Stock Rally Puts Quantum Stocks Back on Wall Street's Growth Radar
SEPTEMBER 22, 2026
AMD Holds $1 Trillion Value as AI Chip Rally Keeps Stock Market Bid
SEPTEMBER 20, 2026
Berkshire Hathaway Stock Faces Succession Test as Buffett Leaves Chair
SEPTEMBER 17, 2026
Tokenized Stocks Get SEC Green Light as Stock Market Tests Onchain Trading
SEPTEMBER 5, 2026
Lululemon Stock Slumps as Guidance Cut Puts Retail Stocks on Demand Watch
AUGUST 31, 2026
GameStop Stock Jumps as Preliminary Profit Outlook Offsets Sales Drop
AUGUST 29, 2026
PayPal Stock Slide Puts Fintech Stocks on Takeover Premium Watch After Stripe Walkaway
AUGUST 28, 2026
Broadcom Earnings Put AI Stocks and Semiconductors on Demand Watch
AUGUST 27, 2026
Russell 2000 Stalls as Treasury Yields Revive Federal Reserve Risk for Small-Cap Stocks
AUGUST 26, 2026
Intuit Stock Slide Puts Software Stocks on Guidance Watch After Fiscal 2027 Outlook
AUGUST 25, 2026
Dick's Sporting Goods Stock Slide Puts Retail Stocks on Foot Locker Watch
AUGUST 24, 2026
Nikkei 225 Index Slide Puts AI Stocks and Semiconductors on Yield Watch
AUGUST 24, 2026
PDD Stock Volatility Puts China Growth Stocks on Temu Margin Watch
AUGUST 23, 2026
Marvell Stock Faces AI Infrastructure Test as Traders Weigh Rich Chip Valuations
AUGUST 22, 2026
Ross Stores Stock Rally Puts Growth Stocks Back on Retail Watch
AUGUST 21, 2026
Nvidia Stock Rebound Puts AI Stocks on Earnings Watch as Yields Test Semiconductors
AUGUST 20, 2026
Stocks Watch Walmart Selloff as Slower US Sales Offset Raised Earnings Outlook
AUGUST 18, 2026
Nasdaq Stock Market Readies 23-Hour Trading as Stocks Face Liquidity Test
AUGUST 17, 2026
Dow Jones Drifts as Stock Indexes Await Retail Earnings Test
AUGUST 16, 2026
SpaceX Stock Rally Puts Growth Stocks on Lockup Supply Watch
AUGUST 16, 2026
Polymarket, Tokenization and Stocks Put Cryptocurrency Market on Liquidity Watch
AUGUST 15, 2026
Russell 2000 Leads Indexes as Small-Cap Stocks Resist Record Pullback
AUGUST 15, 2026
CoreWeave Stock Rally Puts AI Stocks on Margin Watch as Backlog Tops $100 Billion