OCTOBER 21, 2026
Russell 2000 Index Outruns Wall Street as Earnings Breadth Counters Tech DragRussell 2000 strength puts small-cap earnings breadth in focus as Wall Street weighs tech pressure and Fed rate risk.
© 1box.site 2026
OCTOBER 23, 2026
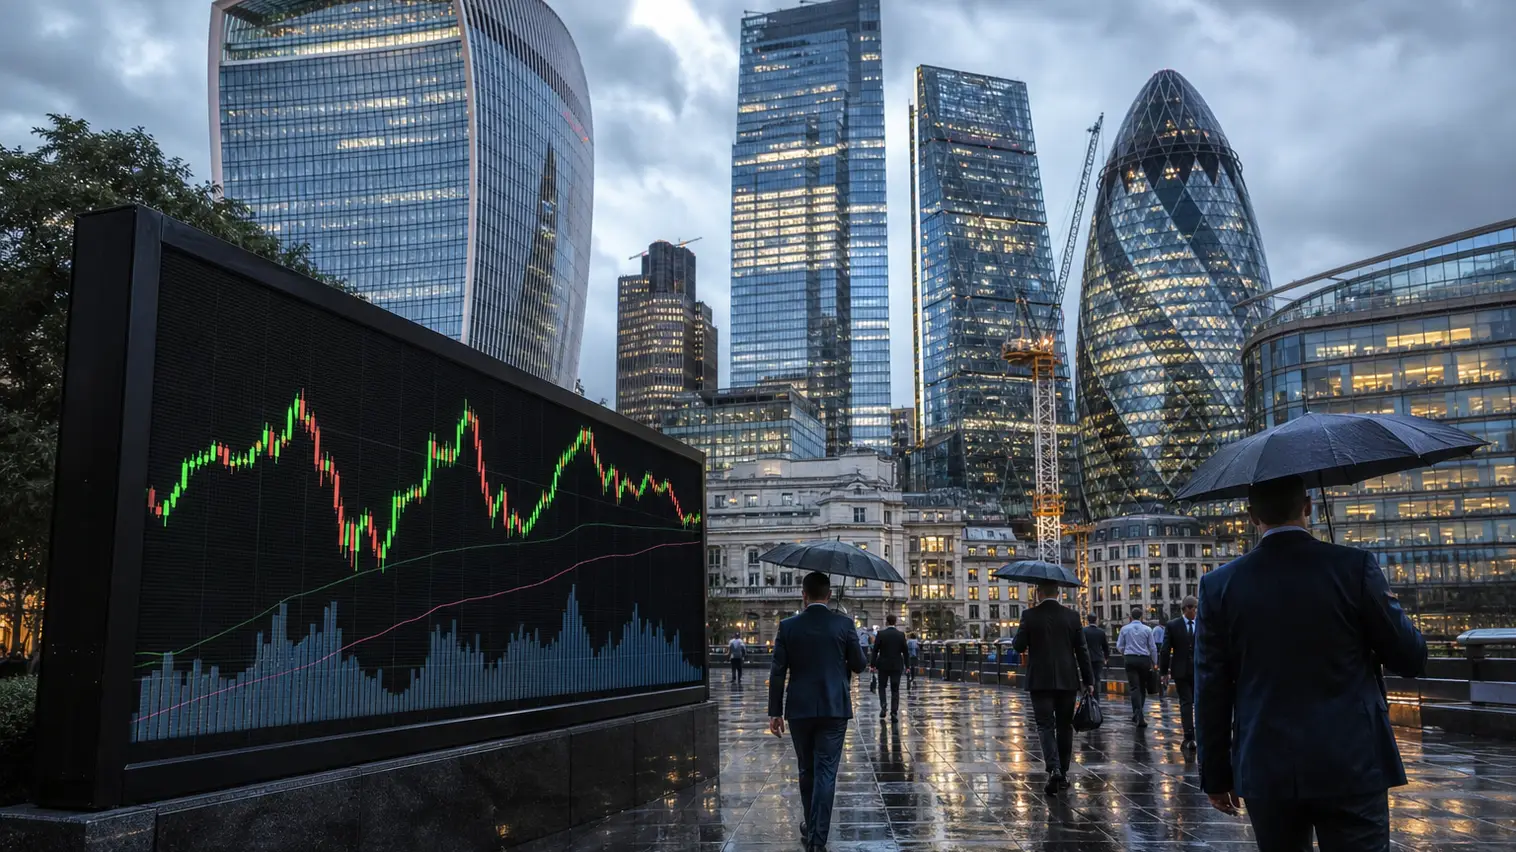
The FTSE 100 moved toward a weekly decline on Friday as investors reassessed the outlook for UK equities after a run of inflation, consumer and corporate signals pointed to a tougher policy backdrop for London-listed shares. The benchmark hovered near the 10,700 area after slipping in the previous session, with traders reluctant to add broad index exposure before next week’s fiscal and monetary-policy catalysts.
The pullback has been less dramatic than the pressure seen in some technology-heavy global benchmarks, but the tone in London has turned more cautious. Higher energy costs, sticky price pressures and a sharp fall in household confidence have revived concern that the Bank of England may have less room to support growth than equity bulls had hoped. That has put the FTSE 100’s defensive reputation under a fresh test.
Thursday’s decline was driven by weakness in banks, miners and selected industrial names, while gains in a handful of company-specific outperformers were not enough to lift the broader market. Mid-cap shares also came under pressure, suggesting that domestic economic worries are beginning to matter more than the overseas earnings support that often helps the FTSE 100 when sterling is soft.
The latest UK inflation reading has become the central issue for the index. Consumer prices rose faster than expected in September, with fuel and other cost-sensitive categories keeping the headline rate well above the Bank of England’s target. For equity investors, the problem is not just the inflation number itself, but what it implies for discount rates, consumer spending and corporate margins into the final quarter.
Rate-sensitive parts of the London market are now facing a more complicated setup. Banks can benefit from higher interest income when rates rise, but that advantage can fade if credit demand weakens, loan losses rise or investors begin to worry about the broader economy. Property, utilities, consumer discretionary names and highly leveraged companies face the opposite problem: higher expected rates can pressure valuations and make refinancing more expensive.
The FTSE 100’s global revenue mix may limit some of the damage from domestic weakness, but it does not make the index immune. A stronger rate-risk premium can still weigh on UK equity multiples, particularly when global investors have competing choices in other markets. London’s relatively high dividend profile remains attractive, yet income support may not be enough if investors decide that earnings forecasts need to be reset lower.
Fresh consumer data added another layer of caution. UK household confidence dropped sharply in October, reaching its weakest level in months and underlining the squeeze from higher living costs. Separate retail figures also pointed to a softer September, with spending momentum looking uneven despite earlier signs of resilience in parts of the economy.
That matters for the FTSE 100 because the index is not only a collection of global miners, drugmakers and energy majors. It also contains retailers, banks, insurers, travel names and consumer-facing businesses that are sensitive to real incomes and sentiment. If households delay major purchases or reduce discretionary spending, the effect can travel quickly from revenue lines to guidance statements.
Investors are therefore watching upcoming company updates for evidence of whether inflation is still being passed through or whether customers are beginning to resist price increases. Margin commentary may become as important as headline revenue growth. A company that reports stable sales but weaker profitability could still struggle to support the index if management points to higher wage, fuel or financing costs.
The next test for the FTSE 100 is breadth. A narrow market led by a few defensive exporters can keep the headline index stable for a while, but a healthier advance would require participation from financials, industrials and consumer names. Recent trading has shown that investors are becoming more selective, rewarding clear earnings resilience while punishing companies exposed to cost pressure or uncertain demand.
Technically, the 10,700 region has become an important short-term reference point. A sustained break below it would risk turning the weekly pullback into a broader consolidation phase, especially if gilt yields move higher or sterling volatility increases before the next Bank of England decision. On the upside, bulls need to see the index reclaim recent highs with stronger volume and wider sector participation.
The FTSE 100 still has potential supports. Its multinational earnings base, commodity exposure and dividend yield can attract investors when volatility rises elsewhere. However, Friday’s setup shows that those supports are being balanced against a domestic macro story that has become less friendly. Until inflation risk eases or corporate results show firmer demand, the London index may continue to trade defensively rather than decisively higher.
For now, the message from the market is measured caution. The FTSE 100 is not in a disorderly selloff, but it is losing some of the momentum that carried it through earlier bouts of global volatility. With the Bank of England rate path back in focus and UK consumers showing signs of fatigue, the index enters the next week with less room for disappointment.
OCTOBER 21, 2026
Russell 2000 Index Outruns Wall Street as Earnings Breadth Counters Tech Drag
OCTOBER 17, 2026
Nikkei 225 Ends Bruising Week as AI Chip Selloff Tests Japan Index Bulls
OCTOBER 16, 2026
Russell 2000 Leads Index Rebound as Treasury Yields Ease After Hot PPI
OCTOBER 14, 2026
Dow Jones Falls as Federal Reserve Rate Fears Hit Index Market After Hot Inflation Data
OCTOBER 13, 2026
FTSE 100 Hits Three-Week High as Bank Stocks and Lower Gilt Yields Lift London Index
OCTOBER 12, 2026
S&P 500 Index Wavers as Wall Street Weighs Oil Shock Before Federal Reserve Inflation Test
OCTOBER 11, 2026
Hang Seng Index Rebounds as Tech Stocks Lift Hong Kong Market Before China Data
OCTOBER 9, 2026
Nasdaq Index Rebound Tests AI Stocks as Treasury Yields Ease
OCTOBER 8, 2026
CAC 40 Index Slides as Europe Weighs France Budget Stress
OCTOBER 7, 2026
Dow Jones Pullback Puts Wall Street Indexes on Federal Reserve Watch as Treasury Yields Climb
OCTOBER 6, 2026
Nikkei 225 Clears 70,000 as AI Index Rally Defies Treasury Yield Risk
OCTOBER 4, 2026
Russell 2000 Leads Index Rebound as Fed Pause Bets Ease Treasury Yield Shock
OCTOBER 3, 2026
Nasdaq 100 Hits Record as AI Leaders Defy Treasury Yield Pressure
OCTOBER 2, 2026
Dow Jones and US Indexes Rise as Jobs Data Pulls Treasury Yields Lower
OCTOBER 1, 2026
FTSE 100 and CAC 40 Slide as Yield Shock Tests Global Index Market
SEPTEMBER 30, 2026
S&P 500 Index Futures Steady as Federal Reserve Inflation Test Keeps Yields in Focus
SEPTEMBER 29, 2026
Russell 2000 Index Slips as Small Caps Face Federal Reserve Yield Test
SEPTEMBER 28, 2026
Hang Seng Index Holds Gain as China Tech Sell-Off Tests Fed-Yield Risk
SEPTEMBER 27, 2026
Nasdaq 100 AI Rally Faces Fed Yield Test as Global Indexes Brace for Data
SEPTEMBER 26, 2026
Dow Jones Leads Index Market Rebound as Treasury Yields Ease From Fed-Driven Peaks
SEPTEMBER 25, 2026
FTSE 100 Rebounds as Softer Oil and Better Consumer Mood Lift London Indexes
SEPTEMBER 24, 2026
S&P 500 Indexes Slip as Federal Reserve Rate Fears Hit Wall Street
SEPTEMBER 23, 2026
Russell 2000 Rebound Puts Indexes on Treasury Yield Watch as Small Caps Test Breadth
SEPTEMBER 22, 2026
Nasdaq Record Leads Indexes as Oil Drop Eases Federal Reserve Yield Pressure
SEPTEMBER 20, 2026
Dow Jones Lag Puts Indexes on Triple-Witching Aftershock Watch as Nasdaq Holds Firm
SEPTEMBER 19, 2026
US Indexes Split as S&P 500 Edges Higher and Federal Reserve Yield Risk Hits Breadth
SEPTEMBER 18, 2026
Russell 2000 Index Rebound Tests Federal Reserve Hike Relief in Index Market
SEPTEMBER 17, 2026
DAX 40 Rebound Leads Index Market as Oil Retreat Eases Yield Shock
SEPTEMBER 16, 2026
Nasdaq 100 Leads Index Futures Rebound as Federal Reserve Decision Puts Yields in Focus
SEPTEMBER 14, 2026
Nikkei 225 Slumps as AI Stocks Put Japan Indexes on Bank of Japan Watch