OCTOBER 29, 2026
Alphabet Stock Plunges as AI Stocks Test Wall Street’s Earnings PatienceAlphabet stock slides after earnings, pressuring AI stocks as Wall Street questions search momentum and data-center spending.
© 1box.site 2026
OCTOBER 26, 2026
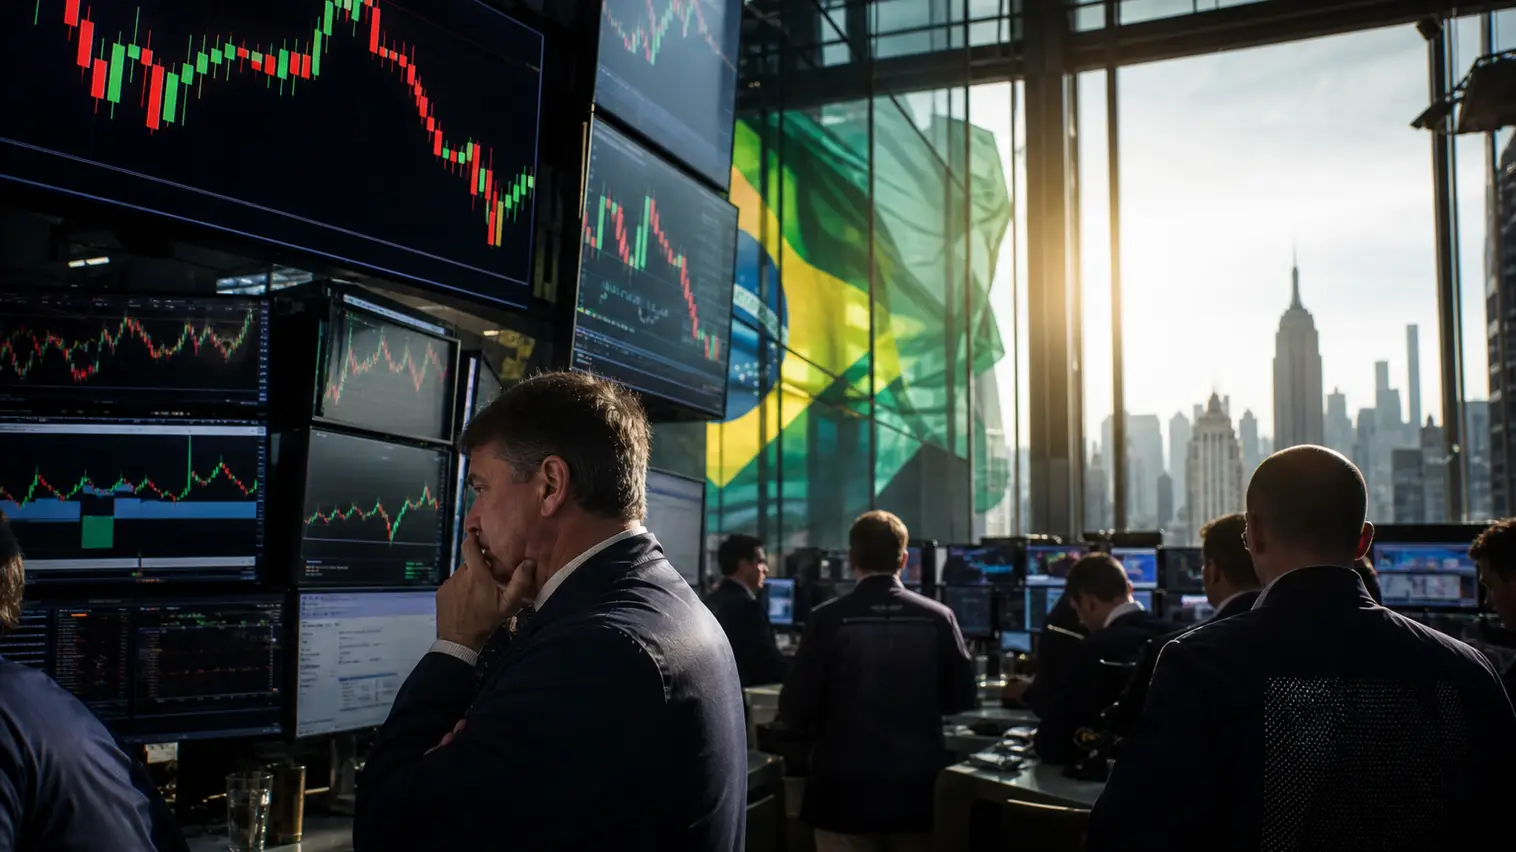
Brazilian stocks became the sharpest pressure point in the stock market on Monday as U.S.-listed shares tied to the country sold off after Luiz Inácio Lula da Silva secured another presidential term in a result that surprised investors positioned for a more market-friendly outcome.
The move gave Wall Street a fresh political risk shock at the start of a week already crowded with Federal Reserve expectations, major corporate earnings and oil-market volatility. While U.S. equity futures were firmer in early trading, Brazil-linked American depositary receipts and exchange-traded exposure pointed to a far more defensive tone inside emerging-market equities.
The selling was broad rather than isolated. Financial technology names, banks, consumer shares and state-linked companies all came under pressure as traders reassessed Brazil’s fiscal path, the outlook for reforms and the risk of heavier state influence in strategic sectors. The scale of the move suggested that investors were not simply marking down one stock, but unwinding a wider bullish Brazil trade built before the runoff vote.
The stock-market reaction reflected a rapid shift in assumptions. Before the vote, parts of the market had priced in a stronger chance of a policy mix viewed as friendlier to privatization, fiscal restraint and corporate earnings. Lula’s victory forced traders to revisit those expectations in a single session, creating a sharp adjustment in ADRs before local investors had fully digested the result.
Nu Holdings and other finance-linked shares were among the most closely watched decliners as investors weighed the effect of a weaker currency, potentially higher local rates and softer foreign appetite for Brazilian risk assets. Petrobras also drew attention because state-controlled companies often trade with a larger political-risk discount when investors fear fuel-pricing intervention, capital-allocation pressure or dividend uncertainty.
MercadoLibre and other consumer-facing names added to the defensive tone. Although some companies have diversified regional revenue streams, Brazil remains a key growth market for Latin American equities. A sudden rise in country-risk premiums can still weigh on valuation multiples, especially for stocks that had previously benefited from optimism around household credit, digital payments and e-commerce penetration.
For global investors, the selloff also revived a familiar emerging-market dilemma: strong long-term growth stories can be quickly repriced when politics, currency markets and local interest-rate expectations move together. That combination can be especially challenging for U.S.-listed ADRs, which trade through New York liquidity and can react immediately to weekend political developments.
The Brazilian real’s weakness was a key part of the equity-market stress. A falling currency can pressure dollar-based returns, raise the cost of imported inputs and complicate the inflation outlook. If the currency slide persists, investors may expect Brazil’s central bank to maintain a restrictive stance for longer, which would raise the discount rate applied to future corporate earnings.
That matters most for growth stocks and lenders. Fintech and bank shares can suffer when credit risk rises, funding costs become less predictable and investors demand a wider margin of safety. Consumer companies also face a more complicated backdrop if currency-driven inflation erodes purchasing power or forces policymakers to stay cautious.
Still, the initial selloff does not automatically define the medium-term path for Brazilian equities. Much will depend on the incoming administration’s early fiscal signals, cabinet choices, budget language and communication with investors. Any credible commitment to spending discipline could stabilize sentiment, while vague or expansionary guidance may keep risk premiums elevated.
The Brazil shock arrived as Wall Street was already preparing for a heavy week of macro and corporate catalysts. Investors are watching whether the Federal Reserve frames oil-driven inflation risks as temporary or as a reason to keep policy tighter for longer. That message could influence demand for emerging-market equities, particularly in countries with visible currency pressure.
At the same time, U.S. earnings season remains central to the broader stock-market tone. If large technology and consumer companies deliver resilient guidance, domestic risk appetite may stay supported even as Brazil-linked stocks trade under pressure. If earnings disappoint, investors may have less tolerance for political shocks and emerging-market volatility.
For now, Brazilian ADRs are likely to remain highly sensitive to headlines around fiscal policy, central bank independence, energy pricing and the shape of the next government’s economic team. Traders will also monitor whether selling spreads from the most liquid ADRs into broader Latin American exposure, or whether bargain hunting emerges after the initial repricing.
The key question for the stock market is whether Monday’s move marks a temporary election shock or the start of a deeper reset in Brazil’s equity risk premium. Until investors see clearer policy direction, Wall Street is likely to treat Brazilian stocks as a high-volatility pocket of the global market, with sharp moves in banks, Petrobras and growth-sensitive ADRs setting the tone.
OCTOBER 29, 2026
Alphabet Stock Plunges as AI Stocks Test Wall Street’s Earnings Patience
OCTOBER 25, 2026
CrowdStrike Stock Leads Cybersecurity Stocks Higher as PHP Flaw Fuels Wall Street Defense Bets
OCTOBER 22, 2026
Nasdaq Leads Index Market Lower as AI Stocks and Oil Shock Hit Wall Street
OCTOBER 21, 2026
Netflix Stock Slide Puts Media Stocks on Wall Street Alert as Ad Forecast Is Cut
OCTOBER 20, 2026
GE Aerospace and RTX Lift Industrial Stocks as Earnings Beats Reset Wall Street
OCTOBER 15, 2026
Morgan Stanley Stock Slips as Record Wealth Revenue Fails to Offset Cost Worries
OCTOBER 13, 2026
Semiconductors Slide as Wall Street Weighs Bank Earnings and AI Rally Risk
SEPTEMBER 23, 2026
IonQ Stock Rally Puts Quantum Stocks Back on Wall Street's Growth Radar