SEPTEMBER 15, 2026
Hang Seng Slips as China Data and AI Hardware Bounce Split Index MarketHang Seng edges lower as weak China demand signals offset an AI hardware rebound and higher yields keep index traders cautious.

© 1box.site 2026
SEPTEMBER 21, 2026
The Hang Seng Index pushed higher on Monday as China-linked equities joined a broader global risk rebound, giving the index market a fresh focal point outside the recent U.S. large-cap rotation. Hong Kong’s benchmark advanced 1.18%, while the Hang Seng China Enterprises Index gained 1.39% and the Hang Seng Tech Index added 0.40%, helped by renewed buying in technology, internet and selected property shares.
The move came as investors positioned ahead of a scheduled meeting later this week between U.S. President Donald Trump and Chinese President Xi Jinping. Traders are watching whether the talks can extend the recent trade truce, reduce pressure around technology restrictions, or at least avoid a new shock to cross-border equity sentiment.
Technology shares provided much of the market’s tone, even though the gain in the Hang Seng Tech Index lagged the broader benchmark. Chip-related and artificial intelligence-linked names were among the stronger performers, while heavyweight internet stocks also steadied after a volatile stretch. The improvement was not a full-scale breakout, but it showed that dip buyers are still willing to re-enter Hong Kong equities when macro risk softens.
Turnover remained an important signal for traders. A rally led by a handful of large technology stocks can lift the headline index quickly, but stronger breadth would be needed to confirm that the advance is developing into a more durable move. Southbound flows also remain under scrutiny because mainland buying has often helped cushion Hong Kong shares during periods of foreign investor caution.
The Hang Seng’s rebound also reflects a wider reassessment of policy risk. Investors are balancing hopes for U.S.-China dialogue against lingering concerns over weak domestic demand, uneven property activity and pressure on corporate earnings. That leaves the index sensitive to any signal from Beijing on fiscal support, credit conditions or measures aimed at stabilizing consumption.
For index traders, the immediate question is whether the Hang Seng can turn Monday’s advance into follow-through above nearby resistance. A sustained move would suggest that regional equity investors are becoming more comfortable with China exposure again. Failure to hold the gains, however, would reinforce the view that the rally is still tactical and heavily dependent on headlines from the summit.
The Hong Kong move was supported by a friendlier global backdrop, with falling oil prices and lower bond yields improving sentiment across equity markets. That matters for China indexes because higher global yields have recently pressured valuations in long-duration technology shares and reduced appetite for emerging-market risk.
Still, the Hang Seng’s recovery remains vulnerable to sudden reversals in currency markets, Treasury yields and geopolitical headlines. A constructive summit outcome could keep buyers focused on technology and consumer shares, while disappointment could quickly shift attention back to earnings risk and capital outflows. For now, the index market is treating Hong Kong as one of the clearest gauges of investor confidence in a possible U.S.-China thaw.
SEPTEMBER 15, 2026
Hang Seng Slips as China Data and AI Hardware Bounce Split Index Market
AUGUST 31, 2026
Hang Seng and Nikkei 225 Drag Global Indexes Lower as Oil Shock Revives Inflation Risk
AUGUST 23, 2026
Hang Seng Rally Puts China Tech and Liquidity in Focus for Indexes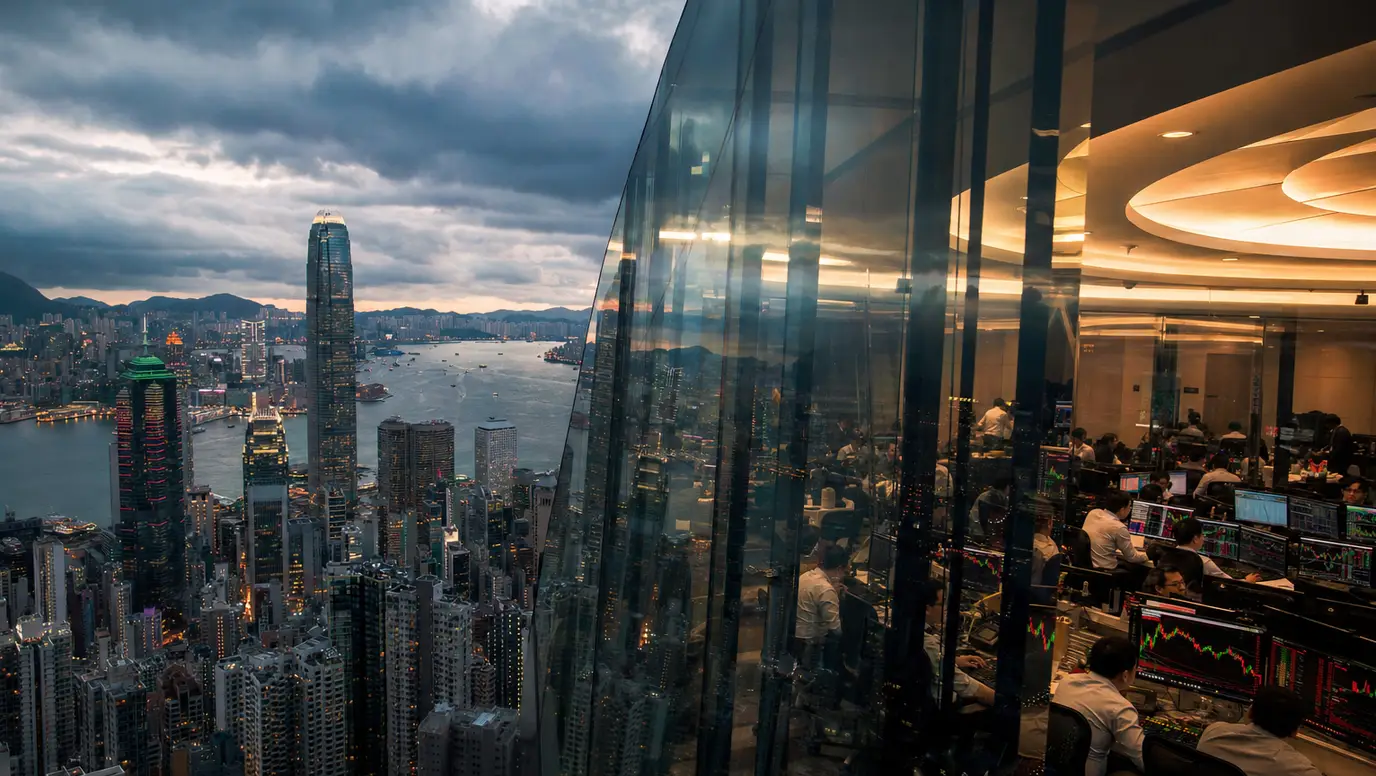
JULY 26, 2026
Hang Seng Slide Puts Indexes on China Risk Watch Before Federal Reserve